

- Signal +1 → open a bear call spread (sell higher delta, buy lower delta call)
- Signal -1 → open a bull put spread (sell higher delta, buy lower delta put)
- Signal 0 → no action; hold existing position
Setup
from typing import Tuple

import pandas as pd
from datetime import datetime
from pulse import (
    Instrument,
    Option,
    InstrumentType,
    PeriodID,
    PeriodType,
    Strategy,
    run_sequentially,
)
from pulse.charts import plot_equity
import plotly.io as pio

pio.renderers.default = "notebook_connected"
Strategy
VerticalSpreadsWithSignals extends Strategy and overrides on_update(). On each pulse it:
- Looks up the current date in
_signals- if no entry exists the signal is 0 (no trade). - Resolves the target expiry using
resolver.expiry.relativewith a minimum DTE filter. - Resolves the short and long strikes by delta using
resolver.strike.delta. - Closes any existing position, then submits two orders to form the spread.
short_delta and long_delta (e.g. 0.30 vs 0.20 → a 10-delta-wide spread).
class VerticalSpreadsWithSignals(Strategy):
    def __init__(
        self,
        underlying_id: str,
        signals: dict[datetime, int],
        long_delta: float = 0.20,
        short_delta: float = 0.30,
        expiry_nearest: int = 1,
        min_dte: int = 30,
        units: float = 1.0,
    ):
        super().__init__(
            name=f"Vertical Spreads with Signals -{short_delta * 100:.0f}d/+{long_delta * 100:.0f}d Spread",
            description=(
                f"Sell or buy vertical spreads based on delta levels. "
                f"Short {short_delta * 100:.0f}d and long {long_delta * 100:.0f}d options."
            ),
            underlying_id=underlying_id,
        )
        self._signals = signals
        self._long_delta = long_delta
        self._short_delta = short_delta
        self._expiry_nearest = expiry_nearest
        self._min_dte = min_dte
        self._units = units

    def _get_signal(self) -> int:
        return self._signals.get(self.last_pulse, 0)

    def _resolve_instruments(
        self, instrument_type: InstrumentType
    ) -> Tuple[Instrument, Instrument]:
        expiration_date = self.resolver.expiry.relative(
            underlying_id=self.underlying_id[0],
            as_of_time=self.last_pulse,
            period_type=PeriodType.MONTH,
            instrument_type=instrument_type,
            nth=self._expiry_nearest,
            period_id=PeriodID.ALL,
            min_dte=self._min_dte,
        )[0]
        short_strike = self.resolver.strike.delta.resolve(
            underlying_id=self.underlying_id[0],
            as_of_time=self.last_pulse,
            expiration_date=expiration_date,
            instrument_type=instrument_type,
            strike_value=self._short_delta,
        )
        long_strike = self.resolver.strike.delta.resolve(
            underlying_id=self.underlying_id[0],
            as_of_time=self.last_pulse,
            expiration_date=expiration_date,
            instrument_type=instrument_type,
            strike_value=self._long_delta,
        )
        ishort = Option(
            underlying_id=self.underlying_id[0],
            instrument_type=instrument_type,
            strike=short_strike,
            expiration_date=expiration_date,
        )
        ilong = Option(
            underlying_id=self.underlying_id[0],
            instrument_type=instrument_type,
            strike=long_strike,
            expiration_date=expiration_date,
        )
        return ishort, ilong

    def on_update(self) -> None:
        signal = self._get_signal()
        if signal == 0:
            return

        if signal == 1:
            ishort, ilong = self._resolve_instruments(InstrumentType.CALL)
        else:
            ishort, ilong = self._resolve_instruments(InstrumentType.PUT)

        self.close_all()

        self.broker.create_order(
            pulse_index=self.pulse_index,
            instrument=ishort,
            quantity=-self._units,
        )
        self.broker.create_order(
            pulse_index=self.pulse_index,
            instrument=ilong,
            quantity=self._units,
        )
Signal Conversion Helper
The strategy expects signals as adict[datetime, int]. This helper converts a DataFrame (with timestamp and signal columns) into that format.
def convert_df_to_signals_dict(
    data: pd.DataFrame, timestamp_col: str = "timestamp", signals_col: str = "signal"
) -> dict[datetime, int]:
    """Convert dataframe with signals to dictionary for the VerticalSpreadsWithSignals strategy.

    Args:
        data (pd.DataFrame): Dataframe with signals
        timestamp_col (str, optional): Column name for timestamps. Defaults to "timestamp".
        signals_col (str, optional): Column name for signals. Defaults to "signal".

    Returns:
        dict[datetime, int]: Dictionary mapping dates to signals
    """
    signals = {
        datetime(
            row[timestamp_col].year,
            row[timestamp_col].month,
            row[timestamp_col].day,
        ): row[signals_col]
        for _, row in data.iterrows()
    }
    return signals
Load Signals
Load signals from a parquet file. Each row has atimestamp and a signal value (+1, -1, or 0).
data = pd.read_parquet("./signals.parquet")
signals = convert_df_to_signals_dict(data)
Run the Strategy
Configure and run the strategy on hourly BTC crypto options (CRY.BTCUSD.DER_1h):
| Parameter | Value | Meaning |
|---|---|---|
long_delta / short_delta | 0.20 / 0.30 | 10-delta-wide spread |
expiry_nearest | 1 | Use the nearest monthly expiry |
min_dte | 7 | Skip expiries with fewer than 7 days remaining |
units | 100 | Contracts per leg |
initial_equity | $1,000,000 | Starting capital |
strategy = VerticalSpreadsWithSignals(
    underlying_id="CRY.BTCUSD.DER_1h",
    signals=signals,
    long_delta=0.2,
    short_delta=0.3,
    expiry_nearest=1,
    min_dte=7,
    units=100,
)

result = run_sequentially(
    [strategy],
    initial_equity=1_000_000,
)[0]

print(f"Strategy run completed successfully in {result.execution_time} seconds.")
Output
Strategy run completed successfully in 0.4869809150695801 seconds.
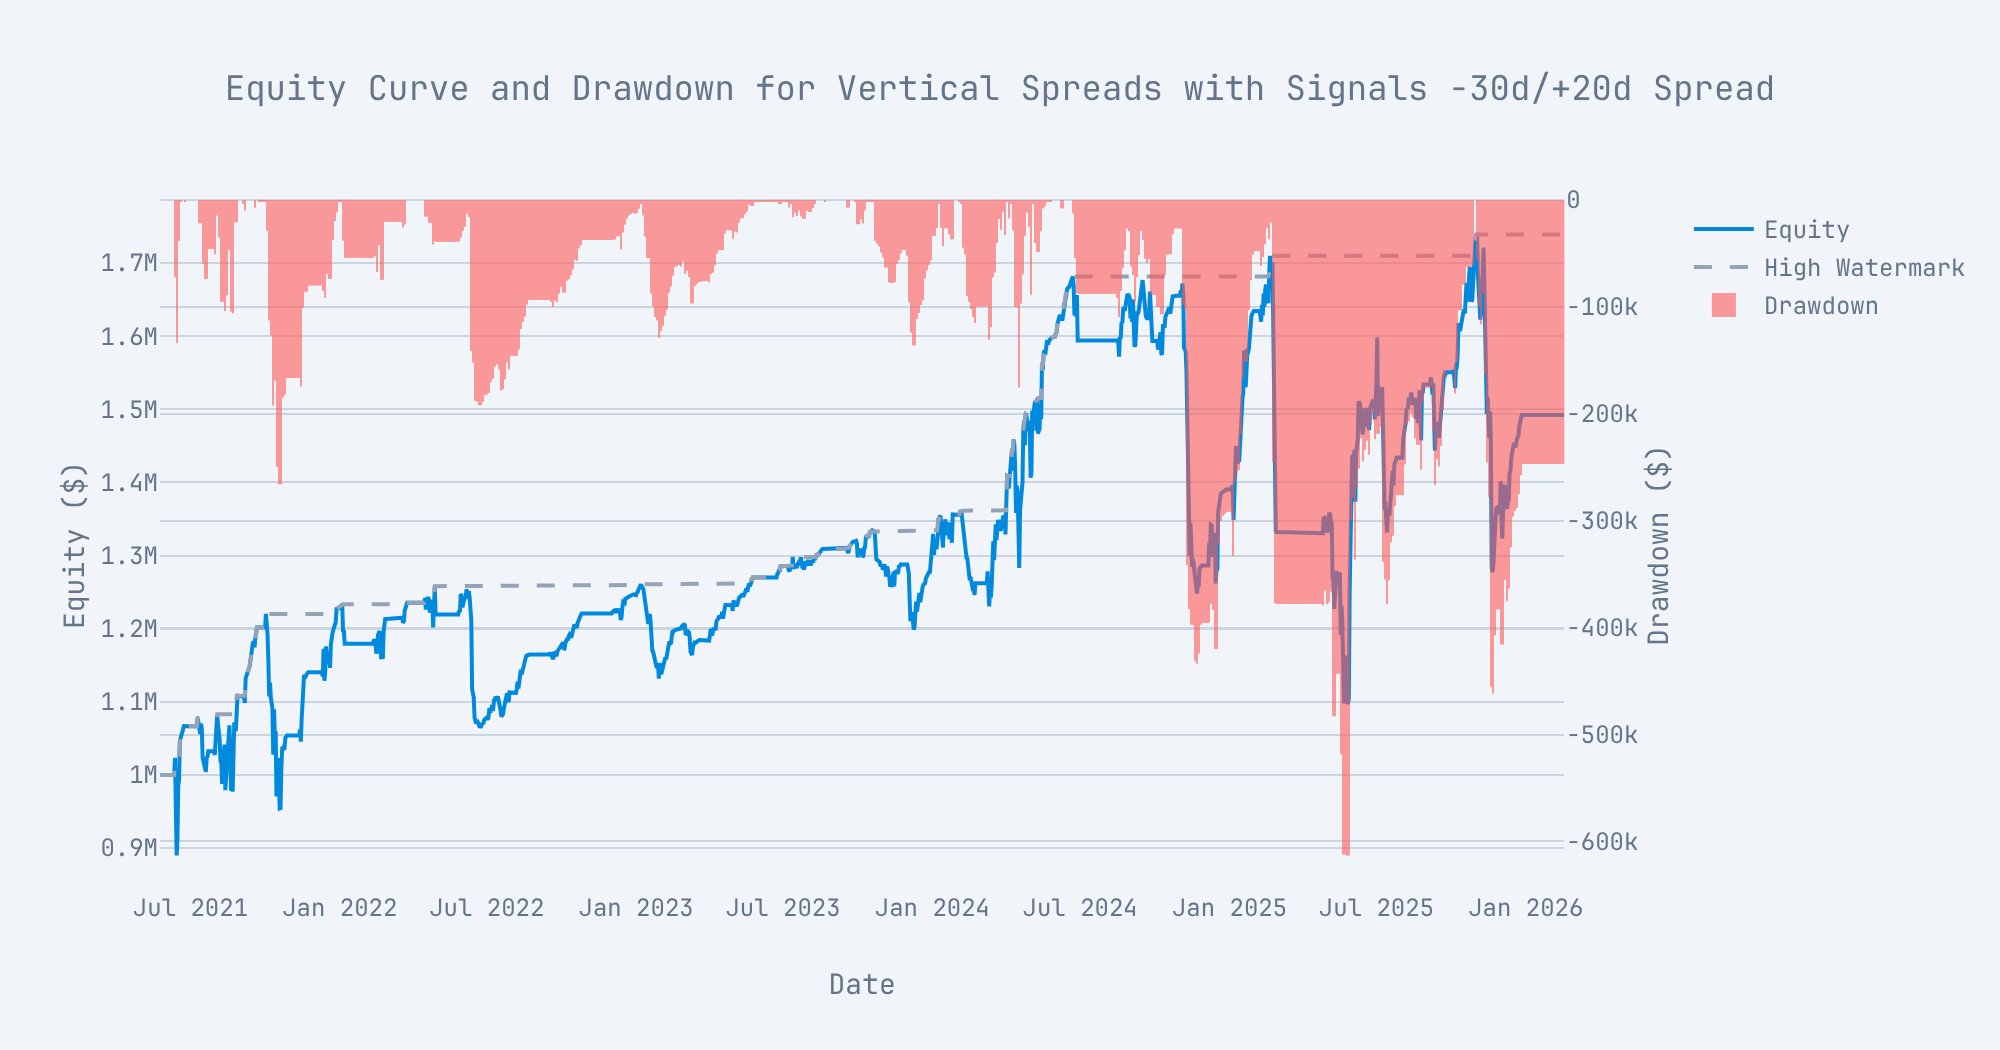
Equity Curve
plot_equity(strategy)
Trades
strategy.trades[-10:]
Output
[<Trade entry: 2025-11-14 00:00:00; exit: 2025-11-21 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.PUT, Strike: 90000.0, Expiration: 2025-11-28 00:00:00>; Quantity: -100; PnL: -69951.70571779017; Cummulative PnL: -392967.83629162126>,
 <Trade entry: 2025-11-14 00:00:00; exit: 2025-11-21 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.PUT, Strike: 85000.0, Expiration: 2025-11-28 00:00:00>; Quantity: 100; PnL: 63556.998007591756; Cummulative PnL: 176688.809636525>,
 <Trade entry: 2025-11-21 00:00:00; exit: 2025-11-28 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.PUT, Strike: 82000.0, Expiration: 2025-11-28 00:00:00>; Quantity: -100; PnL: 924.5414471308891; Cummulative PnL: 167750.06084192026>,
 <Trade entry: 2025-11-21 00:00:00; exit: 2025-11-28 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.PUT, Strike: 78000.0, Expiration: 2025-11-28 00:00:00>; Quantity: 100; PnL: -929.7112510697957; Cummulative PnL: -79087.59177040956>,
 <Trade entry: 2025-11-28 00:00:00; exit: 2025-12-12 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.CALL, Strike: 98000.0, Expiration: 2025-12-26 00:00:00>; Quantity: -100; PnL: 63890.118334027284; Cummulative PnL: 144898.2059516955>,
 <Trade entry: 2025-11-28 00:00:00; exit: 2025-12-12 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.CALL, Strike: 102000.0, Expiration: 2025-12-26 00:00:00>; Quantity: 100; PnL: -27242.59205739727; Cummulative PnL: -97877.46693897425>,
 <Trade entry: 2025-12-12 00:00:00; exit: 2025-12-19 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.CALL, Strike: 94000.0, Expiration: 2025-12-26 00:00:00>; Quantity: -100; PnL: -4366.782433202843; Cummulative PnL: 106052.23401413532>,
 <Trade entry: 2025-12-12 00:00:00; exit: 2025-12-19 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.CALL, Strike: 96000.0, Expiration: 2025-12-26 00:00:00>; Quantity: 100; PnL: -1338.2833681776901; Cummulative PnL: -70744.40576265706>,
 <Trade entry: 2025-12-19 00:00:00; exit: 2025-12-26 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.PUT, Strike: 86000.0, Expiration: 2025-12-26 00:00:00>; Quantity: -100; PnL: 12598.68283949927; Cummulative PnL: 97082.13140116859>,
 <Trade entry: 2025-12-19 00:00:00; exit: 2025-12-26 00:00:00; Instrument: <Option: CRY.BTC.DER, Type: InstrumentType.PUT, Strike: 84000.0, Expiration: 2025-12-26 00:00:00>; Quantity: 100; PnL: -1996.9992947707397; Cummulative PnL: -53235.62329050255>]
Statistics
strategy.stats
Output
Strategy Metrics:
Start Date: 				2021-05-25 00:00:00
End Date: 				2026-02-17 00:00:00
Duration: 				1730 days, 0:00:00
***********************************************************
Total Return (%): 			49.22
CAGR (%): 				8.82
***********************************************************
Start Equity ($): 			1000000.00
End Equity ($): 			1492214.60
Diff ($): 				492214.60
***********************************************************
Annualized Sharpe Ratio: 		0.31
Calmar Ratio: 				0.00
Annualized Sortino Ratio: 		0.42
***********************************************************
Daily Mean Return (%): 			0.02
Daily Volatility annualized (%): 	1.42
Best Daily Return (%): 			12.20
Best Day Date: 				2025-05-30 00:00:00
Worst Daily Return (%): 		-12.54
Worst Day Date: 			2025-11-20 00:00:00
***********************************************************
Monthly Mean Return (%): 		1.00
Monthly Volatility annualized (%): 	26.19
Best Monthly Return (%): 		17.56
Best Month Date: 			2025-01
Worst Monthly Return (%): 		-22.29
Worst Month Date: 			2024-11
MTD Return (%): 			0.00
3-Month Return (%): 			10.03
Positive Months (%): 			64.91
Average Up Month (%): 			4.91
Average Down Month (%): 		-8.31
***********************************************************
6-Month Return (%): 			-2.74
Year-to-Date Return (%): 		0.00
1-Year Return (%): 			12.02
Yearly Mean Return (%): 		4.01
Yearly Volatility annualized (%): 	3.43
… (32 more lines)