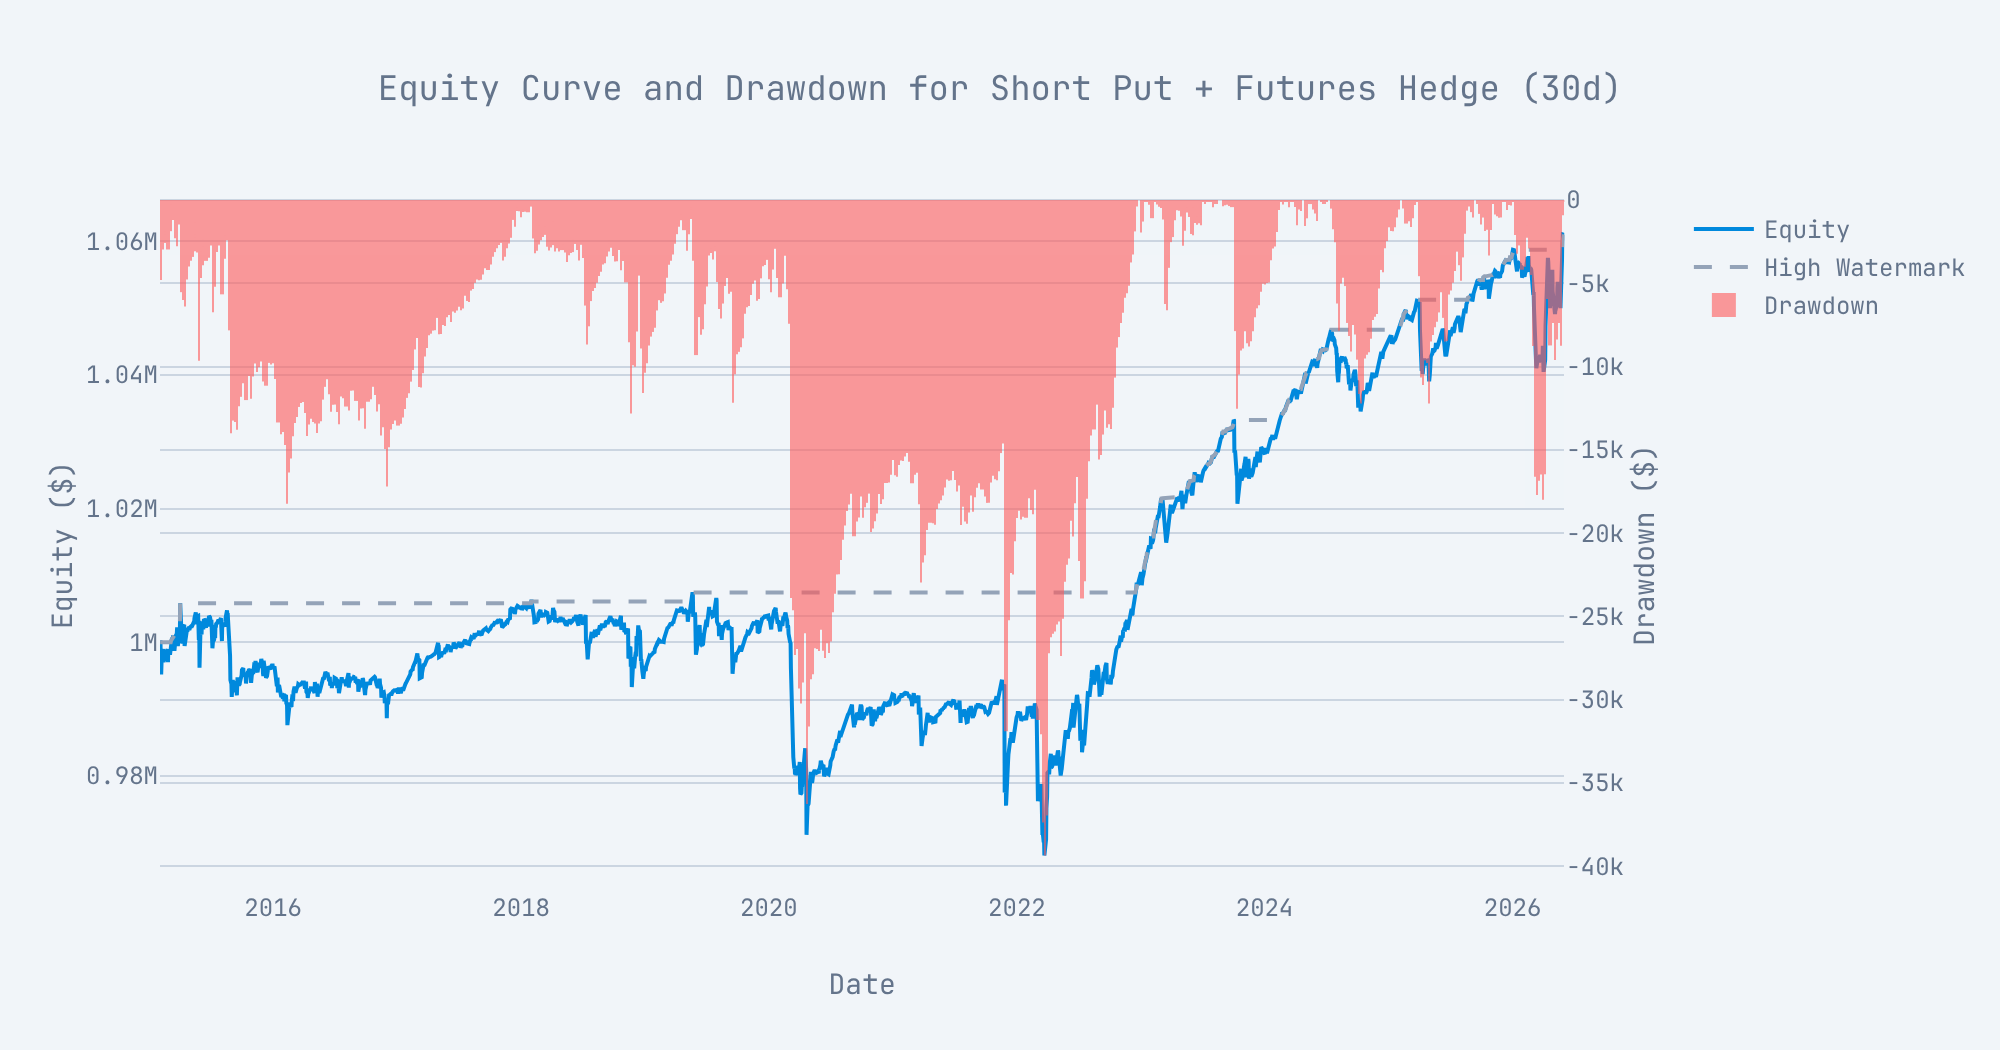
COM.BRN), then neutralise the position’s delta each pulse by trading a front-month future - the building block behind the delta-hedged strangle.
What this shows
- Reading a live delta from the datafeed.
- Sizing a futures hedge to offset the option delta (a future has delta 1).
- Rolling the put monthly and rebalancing the hedge in place with
trade.rebalance(...).
Output
Equity