

- Datafeed - Access market data for options, futures, and other instruments
- Resolver - Convert relative parameters (delta, moneyness) into concrete values
- Strategy Framework - Build custom trading strategies with maximum flexibility
- Execution Engine - Run backtests with realistic order execution and portfolio management
- Performance Analytics - Track P&L, risk metrics, and equity curves
Resolver
The Resolver component translates relative parameters into concrete values. For example, it can convert a “25-delta put” specification into an actual strike price at a specific point in time and expiration date.Resolving expiration dates
The expiry resolver finds expiration dates based on criteria such as minimum days to expiration (DTE) and Nth front month. In this example, we’re finding the first monthly expiration for call options on Brent crude oil that has at least 14 days to expiration as of January 2, 2020.min_dte is required: there is no implicit default, so every resolved expiry states how much time it needs.
Output
Resolving strikes
The strike resolver converts delta values into actual strike prices. Here we’re finding the strike price for a 25-delta put option using the expiration date we resolved above.Output
Datafeed
The Datafeed component provides access to financial market data, including options, futures and spot instruments. It ensures no forward-looking bias by requiring anas_of_time parameter for all data requests. as_of_time represents the current time in the backtest, and can be accessed in strategies via self.last_pulse. It is matched exactly against the prepared settlement datetimes, so it must be a datetime the underlying actually has (datafeed.reference.available_settlements(...) lists them).
Output
Output
Simple strategy
Now we’ll implement a complete trading strategy that demonstrates how to combine all Pulse components. This strategy will sell put options monthly based on delta targeting.Importing Strategy Components
These imports provide the core classes and functions needed to build and execute trading strategies.Strategy Implementation
TheShortPut class demonstrates a complete trading strategy implementation. It inherits from the Strategy base class and implements custom trading logic in the on_update() method.
Key features of this strategy:
- Monthly rebalancing: Opens new positions at the start of each month
- Delta targeting: Sells put options at a specified delta value
- Position sizing: Uses a percentage of available equity for position sizing
- Automatic expiration management: Resolves expiration dates based on minimum DTE criteria
Strategy Execution
To run a backtest, we initialize the strategy with specific parameters and pass it to therun_sequentially function along with initial capital.
Output
Visualizing Results
After execution, we can visualize the strategy’s performance using the built-in charting functionality. This creates an interactive equity curve showing how the strategy’s value changed over time. You can easily access detailed performance metrics and trade logs for further analysis.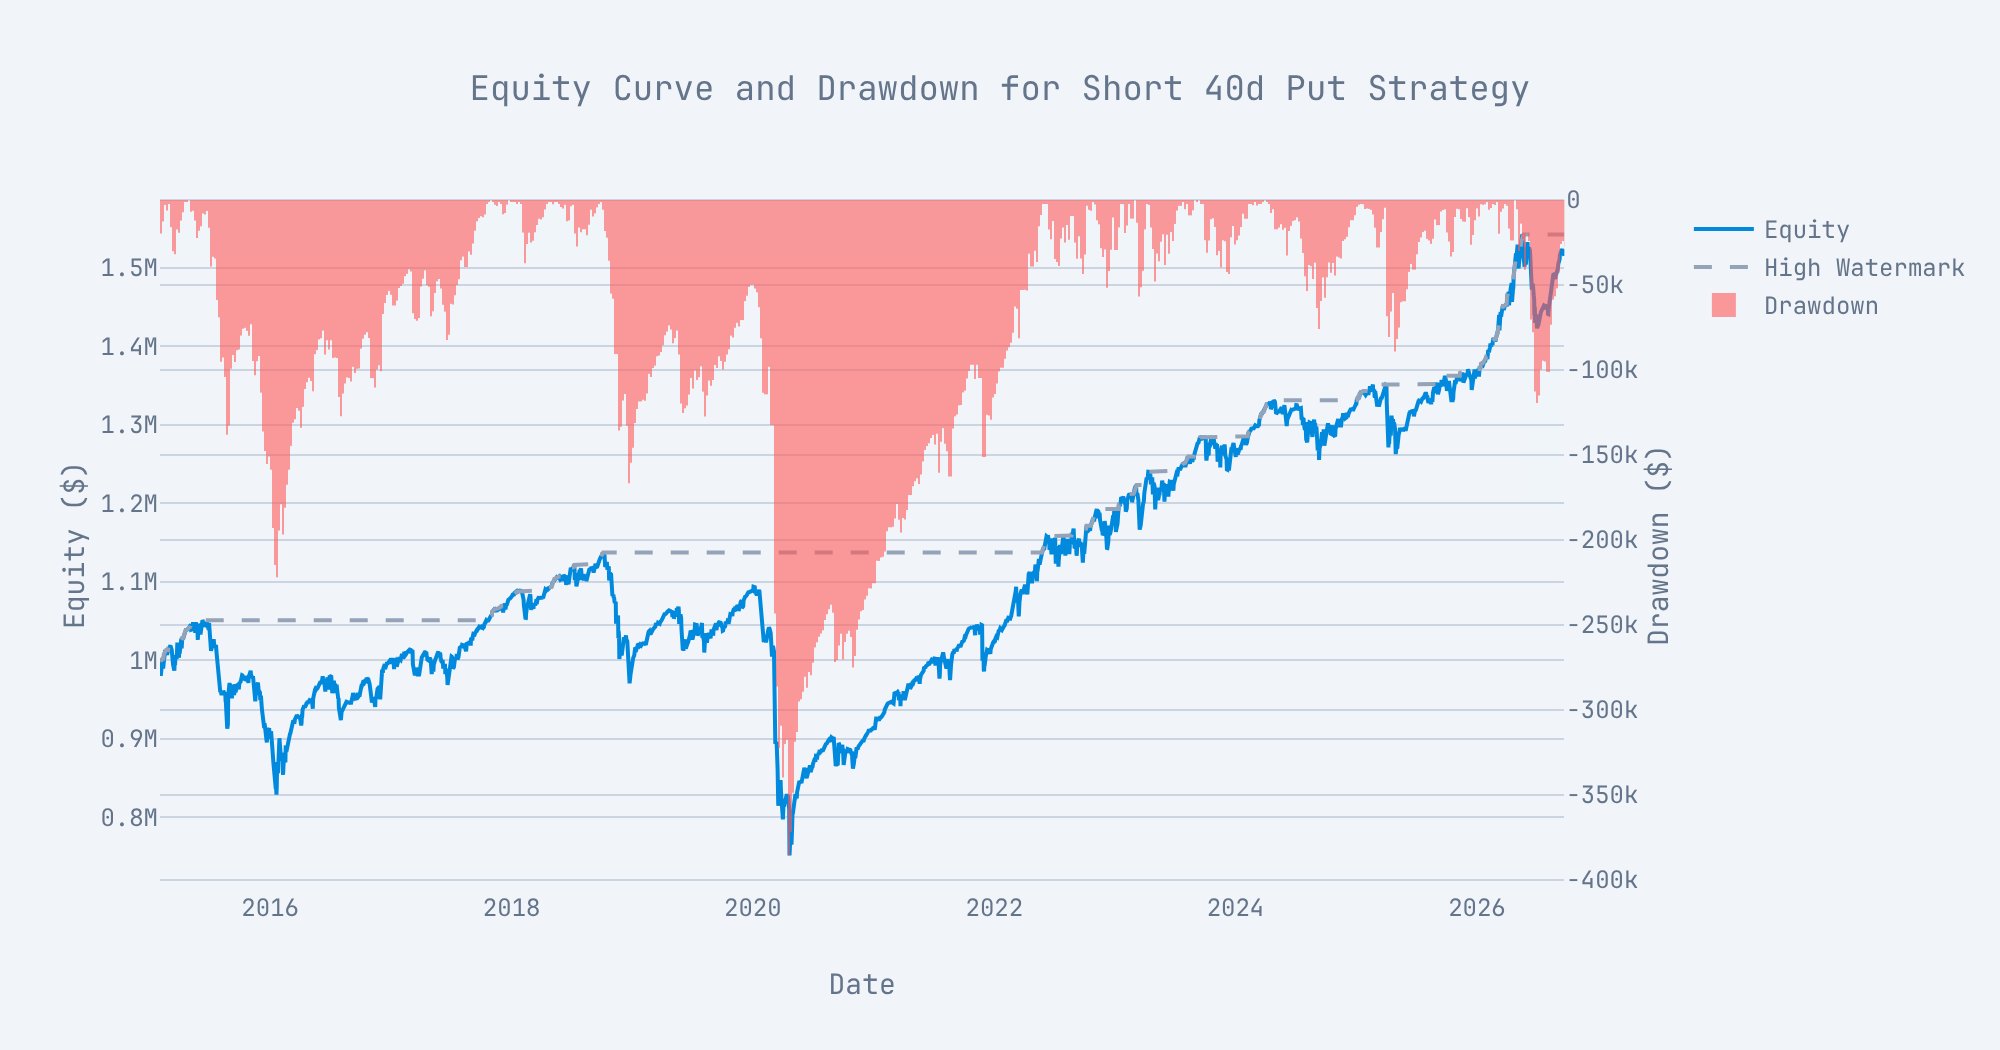
Accessign Performance Metrics
Output
Accessing P&L History
Output
Output
Output
Accessing Trades
Output