

Description
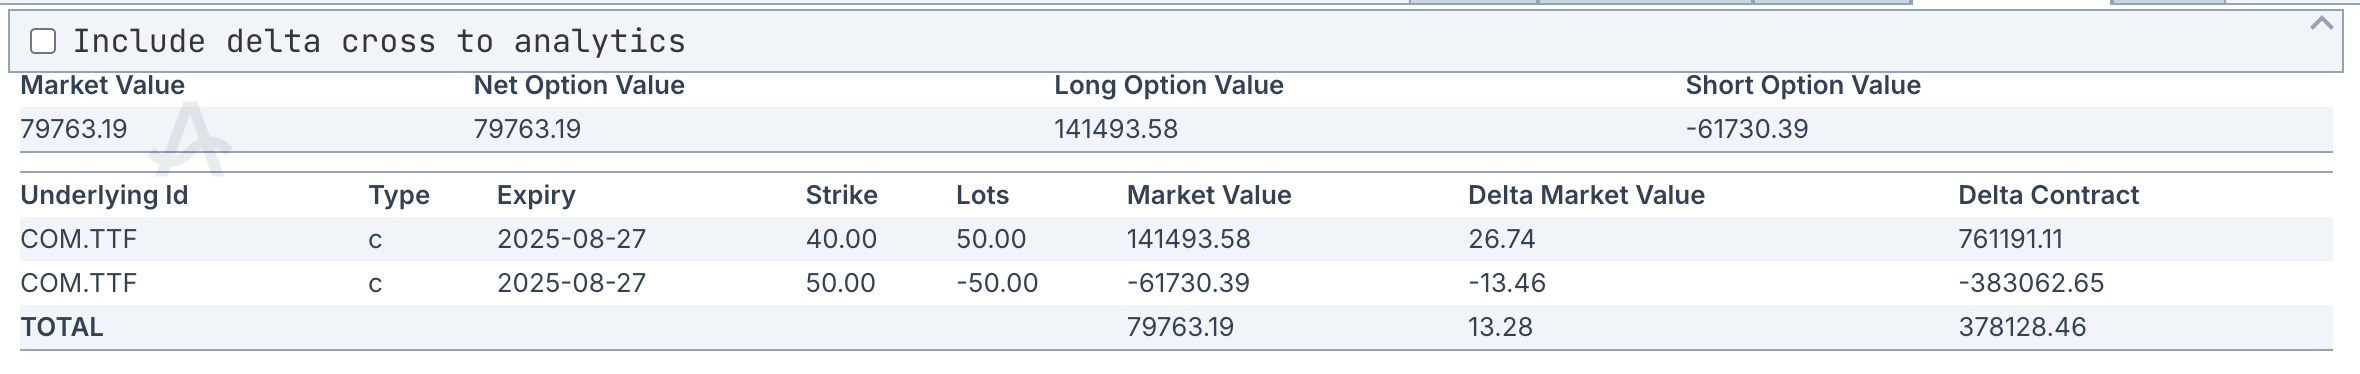
The Risk Metrics Table offers a transparent breakdown of a structure’s market value, directional exposure, and delta risk by option leg. It is designed for risk managers and traders who need clear and immediate visibility into the economic impact of current positions. This table summarises key risk and valuation metrics across the structure’s constituent legs, including:- Total market value of the structure
- Separation of long vs short option value
- Delta exposures at market value and contract levels
Interactive Controls

- Include delta cross to analytics - Add cross to the analytics with the selected structure.
Table Components
Header Summary

Leg-Level Breakdown Table

- Underlying Id - Identifier of the underlying asset.
- Type - Option type: c = Call, p = Put.
- Expiry - Option expiration date.
- Strike - Strike price of the option.
- Lots - Quantity held (positive = long, negative = short).
- Market Value - Current mark-to-market value of the leg.
- Delta Market Value - Dollar value sensitivity to underlying moves.
- Delta Contract - Sensitivity in contract units — useful for hedge sizing.
Total Row
- Aggregates all metrics across the entire position.
- Gives a high-level view of total directional bias and market risk.
Interpretation Tips
- Delta Market Value vs Delta Contract:
- The first shows dollar exposure.
- The second helps determine how many contracts to buy/sell for hedging.
- Positive Net Delta: Strategy benefits from rising underlying.
- Negative Net Delta: Strategy profits from underlying falling.
- Large Short Option Value: May signal premium collection strategies (e.g., spreads).
- Unbalanced Delta: Suggests directional exposure — may need hedging.
Allasso Trade’s charts and interpretation tips describe market data and past behaviour. They are not a
forecast, and nothing in them is investment advice.